Categories
GeneralPublished September 6, 2026
9 Wind Mitigation Discounts Baldwin County Homeowners Can Claim
9 Wind Mitigation Discounts Baldwin County Homeowners Can Claim
Wind mitigation discounts in Alabama are written into state law, not offered as a courtesy, and Ala. Code 27-31D-2 requires them on insurable property anywhere in the state.
Knowing which credit a house qualifies for is only half of it. Each one wants different proof, and a different person has to sign off.
Here are nine credits a Baldwin County homeowner can claim, the evidence each needs, and who inspects for it.
The nine credits, and what each one needs:
1. What is a wind mitigation inspection, and who is allowed to do one?
In Alabama the inspection that earns a wind credit is a FORTIFIED evaluation, and only an accredited FORTIFIED Evaluator can perform it. The evaluator issues a Current Condition Report. That report names the assemblies and systems that already meet the standard. It also lists the retrofits needed for a designation, and any conditions that have to be fixed first.
A strong evaluator hands over the Current Condition Report in writing, with photographs, and the retrofits listed in cost order. Ask for the evaluator's accreditation. Baldwin County homeowners should also ask which items can wait for the next roof replacement.
A general home inspector offering a wind mitigation inspection is not the same credential. A report from the wrong inspector can be rejected by the carrier, and the owner pays twice. Not every inspector will say so upfront.
2. Which discount does Alabama law actually require my insurer to give?
Alabama law requires insurers to provide a premium discount or rate reduction for property built or retrofitted to IBHS FORTIFIED standards, under Ala. Code 27-31D-2. The adjustment has to be actuarially justified. The state insurance department announced the range in Bulletin 2016-07. On the hurricane portion of the premium the discount runs 35 to 60 percent. On the other wind portion it runs 20 to 35 percent.
Ask the carrier for its filed mitigation discount schedule in writing, and for the dollar amount the credit produces on this policy. The credit applies to the wind and hurricane portion, so ask what share of the premium that portion is.
A quote that gets cheaper with no line item naming the mitigation credit has not applied one. The honest grey: the percentage is a range, each carrier files its own numbers inside it, and a small wind portion means a small change.
3. What does a FORTIFIED Roof designation take, and what does it earn?
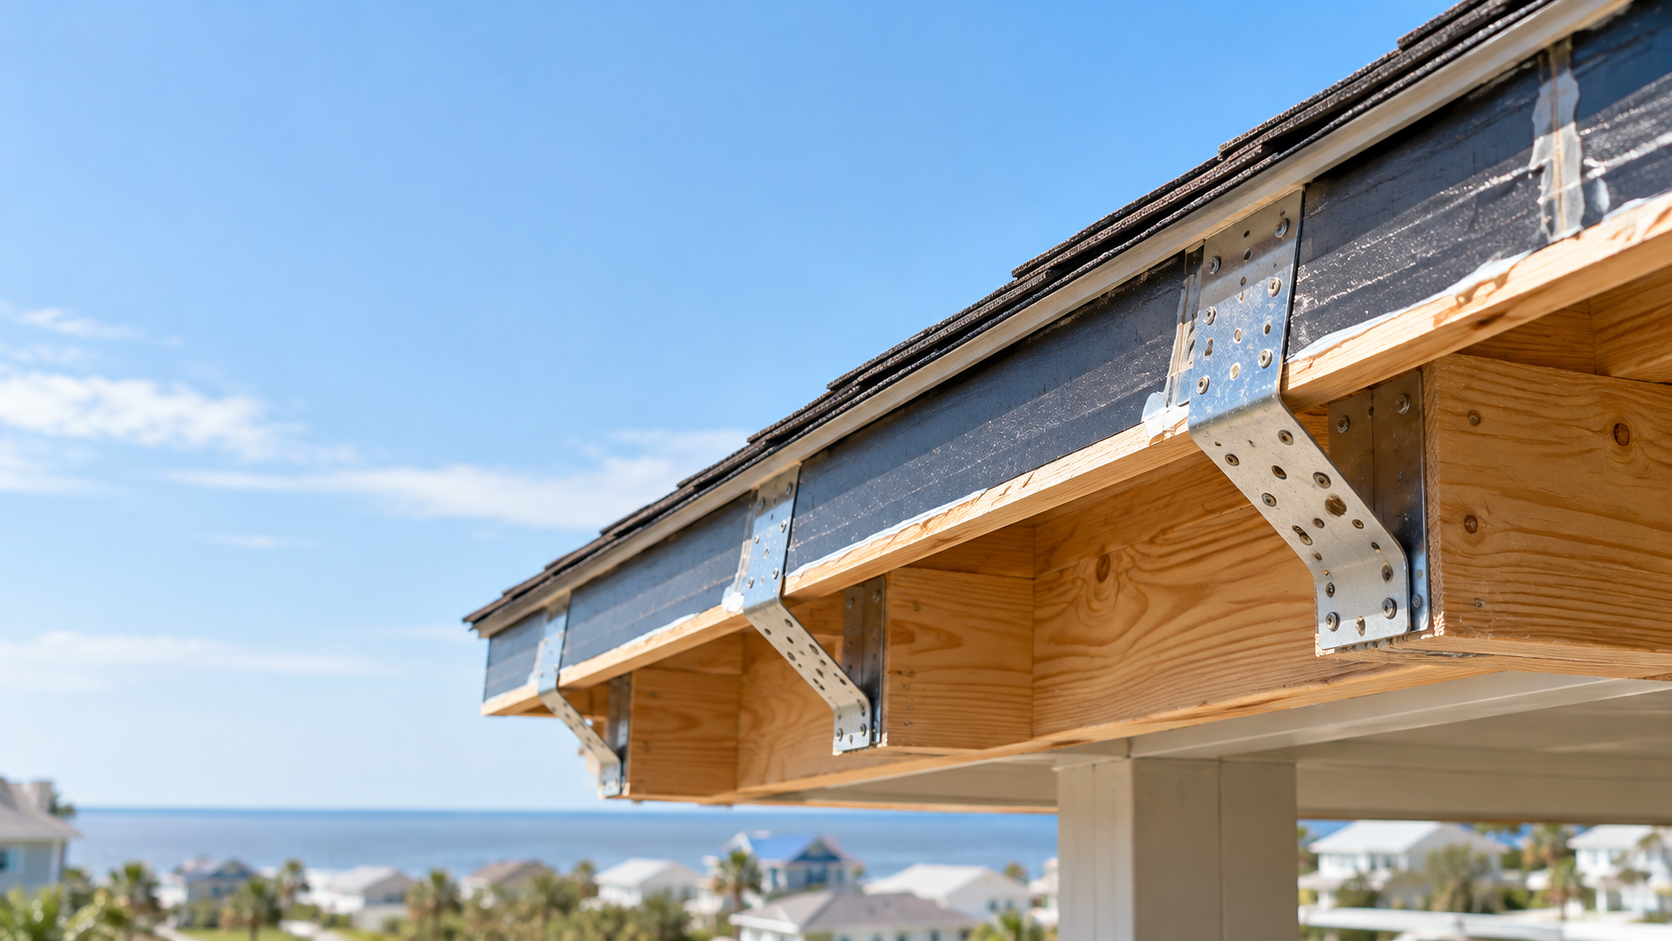
FORTIFIED Roof is the entry designation and it rebuilds the roof, not the whole house. It requires a sealed roof deck and ring-shank nails in an enhanced pattern. It also requires a wider drip edge with a fully adhered starter strip, rated roof covers, and attic vents that resist wind-driven rain. It is normally earned at the next roof replacement.
The checkable step is hiring a FORTIFIED-trained roofer and having the evaluator document each layer before it is covered. Keep the certificate and the photographs. Orange Beach realtors see that certificate come up again at resale, because the next buyer's insurance quote depends on it.
A roofer who says the new roof is just as good without the designation is describing shingles, not paperwork. No certificate means no filed discount. The work and the credit are two separate things.
4. What does FORTIFIED Silver add beyond the roof?
Silver protects the openings and the pieces attached to the house. It adds impact and pressure rated garage doors, chimney bracing, anchored attached structures such as carports and porches, and gable end bracing. In hurricane-prone areas it also requires impact protection for windows and doors, plus reinforced soffits.
Ask the evaluator which Silver items the house already satisfies. Many Baldwin County homes built in the last twenty years already carry rated garage doors and braced gable ends. That shortens the list. Get the product approval numbers for any window, door or shutter being claimed.
Plywood cut to fit is not opening protection for credit purposes. Tested and rated assemblies are what the standard asks for, and a carrier can ask for the product documentation years later at a claim.
5. What does FORTIFIED Gold add, and is it worth it on an existing house?
Gold includes everything in Silver and adds an engineered continuous load path. That means the connections are engineered as one structure, not protected piece by piece. It covers roof-to-wall, story-to-story and wall-to-foundation. On a new build it is a design decision. On an existing house it usually means opening up walls, so it is the hardest level to reach after the fact.
Ask for a written comparison: the cost to reach Gold against the extra credit over Silver on this carrier's filed schedule. For a house being gutted or rebuilt anyway, the engineering is already on the table and the answer often changes.
Chasing Gold on a finished house because it sounds like the best option is how owners spend more than the credit returns. Silver is the level most existing Baldwin County homes can reach without demolition, and saying so is not a lack of ambition.
6. Can the state pay for the work instead of me?
Strengthen Alabama Homes pays 100 percent of the cost of mitigation up to $10,000 toward a FORTIFIED Roof, which may not cover the whole job. The state insurance department runs it. It is limited to existing owner-occupied single-family homes, and the home cannot be listed for sale during the process. Grants also open only in the counties on the program's current grant award schedule, so check that Baldwin County is on it.
The application asks for proof of an in-force homeowners policy with wind coverage. Flood insurance is also required if the home sits in a special flood hazard area. It ends with the owner uploading a new declarations page showing the discount.
Rentals, townhomes, condominiums and mobile homes are excluded, and the program says so plainly. That is worth knowing before a contractor quotes work on the assumption the state will cover it.
7. If a storm already took my roof, do I have to pay to upgrade it?
Alabama law puts part of that on the insurer. Under Ala. Code 27-31D-2.1, an insurer writing homeowners coverage must offer a fortified bronze roof endorsement to upgrade a nonfortified home when covered damage requires a roof replacement. The offer has to be extended when the policy is written and at the first renewal following January 1, 2020.
Check the policy for the endorsement before a storm, not after. Ask the agent in writing whether this policy carries the fortified roof endorsement and what it pays. If the answer is no, ask what it costs to add at renewal.
Assuming a replacement roof gets built to the standard automatically is the costly mistake. A claim pays to put back what was there. The upgrade is a separate coverage decision, and it has to sit in the policy before the storm.
8. What credits does AIUA give on a wind-only policy?
The Alabama Insurance Underwriting Association is the state's wind insurer of last resort, and it writes only in Baldwin and Mobile counties. AIUA offers premium discounts to owners who build to fortified standards or install wind loss mitigation features. Its own list names hurricane wind resistive shingles, roof straps, and impact resistant doors, windows and shutters.
Send AIUA the designation certificate or the evaluator's report, and ask for the discounted premium in writing before binding. One more thing to check: AIUA policies do not include flood, so a home in a flood zone still needs a separate flood policy.
Owners sometimes treat the last resort market as the only option without shopping the admitted market first. It is worth a quote from both, because a fortified home is exactly the risk a private carrier is willing to write.
9. Does a newer code-built home earn anything without a FORTIFIED designation?
It can. The Alabama Department of Insurance handout on windstorm damage mitigation, published in December 2014, lists homes built to the 2006 International Residential Code or later as a discount category alongside the FORTIFIED levels. That handout is dated, so confirm the category with the carrier's current filed schedule. Coastal Baldwin County sits in a windborne debris region, and the residential code requires opening protection there.
Pull the permit file from the city building department. In Orange Beach, where Heather Loper & Associates works, that file can include a wind load compliance certificate. The certificate names the code edition, the ultimate design wind speed and the exposure class.
A listing that says built to current hurricane code is not evidence. The permit record and the certificate are. Owners who cannot produce either usually end up paying for an evaluation to prove what the house already has.
What each level adds, and the paperwork a carrier asks for before it files the credit.
| Level | What it adds | Evidence the carrier wants |
|---|---|---|
| FORTIFIED Roof | Sealed deck, ring-shank nails, rated edge and vents | Designation certificate from the evaluator |
| FORTIFIED Silver | Opening protection, rated garage door, gable and chimney bracing | Product approvals plus the certificate |
| FORTIFIED Gold | Engineered continuous load path | Engineer's design plus the certificate |
| Recent code build | Opening protection required in the debris region | Permit file and wind load compliance certificate |
Frequently Asked Questions
Why is Alabama home insurance so high?
Coastal exposure drives it. Baldwin and Mobile counties sit on the hurricane coast. That is why Alabama runs a wind insurer of last resort for those two counties alone. The mitigation discounts themselves are required statewide, and they matter most here. Premium follows expected wind and surge loss, so the two levers an owner controls are the building itself and the deductible.
Does a wind mitigation discount lower my flood insurance too?
No. Flood is a separate policy and wind credits do not reach it. AIUA policies, for example, exclude flood entirely, so a home in a flood zone needs its own flood coverage. Elevation, not roof straps, is what moves a flood premium.
Will my insurer apply the discount automatically once the work is done?
Usually not. The designation certificate has to reach the carrier, and the credit shows up on the next declarations page. The state grant program makes that its own final step: the owner uploads the new declarations page showing the discount. Compare the renewal with the prior term and ask if the line is missing.
Do condo owners get wind mitigation discounts?
It depends on who insures the structure. In most condominium buildings the roof and the exterior openings sit under the association's master policy. Mitigation work there affects the association's premium rather than a unit owner's contents policy. Owners should ask the association whether the building holds a designation and what the master policy deductible is.
Who pays for the FORTIFIED evaluation?
The owner does, outside of the grant program. Inside the state grant process, selecting a certified evaluator and completing the evaluation are steps the program walks the owner through. Either way the evaluation comes first, because its report is what tells a contractor what the house actually needs.
Ask Heather Loper & Associates what a fortified home is worth here
Heather Loper & Associates works Orange Beach and Gulf Shores, where a FORTIFIED certificate changes both the insurance quote and the buyer pool. Owners weighing the work before a renewal can reach the team at (251) 504-1171. Sellers comparing the best real estate agents in Orange Beach can start there too, or message through heatherloper.com.
This article is general information about Alabama insurance law and state mitigation programs. It is not legal, tax or insurance advice. Check your own policy and situation with a licensed agent or an attorney.
or another way