Categories
BuyerPublished August 20, 2026
8 Things to Know About Flood Zones Before Buying in Gulf Shores
8 Things to Know About Flood Zones Before Buying in Gulf Shores
Flood zones in Gulf Shores decide how a house is built, what a lender demands and what the insurance costs for as long as it is owned.
Most pages answering the AE and VE question are written for a national audience rather than for the Alabama coast.
These eight points come from the city, Baldwin County and the federal rules that sit behind both.
Each one names what to ask for and when.
The eight points, in short:
-
The difference between AE and VE
-
Looking up the zone for an address
-
Elevation certificates and where to find one
-
How flood premiums are priced now
-
When a lender requires flood coverage
-
What a federal flood policy pays
-
The substantial improvement 50 percent rule
-
Flood history and Alabama disclosure
1. Which flood zone is worse, AE or VE?
Both are special flood hazard areas, meaning a 1 percent or greater chance of flooding in any year. VE is the coastal high hazard zone. It is mapped where the base flood brings high velocity wave action, defined as a 3 foot breaking wave. AE covers land flooded by the same base flood without that wave force. VE carries the stricter building rules.
A strong answer also raises the Coastal A Zone. That is the part of an A zone just landward of a V zone, where wave heights run below 3 feet. The boundary is mapped as the Limit of Moderate Wave Action, where base flood wave heights fall between 1.5 and 3 feet. Ask whether the address sits inside it.
Treating AE as safe because it is not VE is the misread to avoid. AE is still a mapped high risk zone with a base flood elevation and a lender requirement attached. A house one lot behind the AE line can take the same surge as the one in front of it.
2. How do I find out which flood zone an address is in?
The zone comes from the current Flood Insurance Rate Map, not from a listing sheet or a neighbor. Gulf Shores publishes a guide titled How to Identify if You're Located in an AE or VE Flood Zone. The city also runs a floodplain management program and points residents to FEMA and FloodSmart resources for lookups.
A strong answer prints the map panel with the property outlined and notes the date on it. Zone lines follow the parcel, not the street, so one subdivision can hold two zones. Ask the city building department to confirm the zone in writing before the inspection period ends.
A listing that names a zone with no panel behind it is repeating something typed years ago. Maps get revised. Where an update moves a property into a high risk zone, a policy bought within 12 months of that update carries a one day wait instead of thirty.
3. What is an elevation certificate, and does the house already have one?
An elevation certificate records how high a building sits against the base flood elevation. Baldwin County requires the certificate to be prepared, signed and sealed by a land surveyor or engineer licensed in Alabama. The county keeps certificates in a database and asks anyone who cannot find one for an address to email its building department permitting office.
A strong answer asks for the existing certificate first, then prices a new survey only if none turns up. Read the lowest floor elevation and set it against the base flood elevation on the panel. The gap between those two numbers is the most useful figure in the whole file.
A seller who says the house sits above the flood level without a certificate is offering a memory. So is an agent who calls the certificate optional because the map already shows a zone. The map describes an area. The certificate describes the building.
4. Does the flood zone still decide what I pay for insurance?
Not on its own. Under Risk Rating 2.0 the National Flood Insurance Program prices each building rather than each zone. Rating uses flood frequency, the flood types a property faces, distance to a flood source, first floor height and the cost to rebuild. New policies were priced this way from October 1, 2021, and all policies moved across by April 1, 2022.
A strong answer is a quote on the exact address, run for the buyer's own coverage amounts. Ask for it early, because the figure can change the offer. Private flood carriers also write on the Alabama coast, so a second quote outside the federal program is worth the phone call.
Quoting the seller's premium as the buyer's is the common error, and it is not always conservative. Rating follows the building, the coverage chosen and the deductible chosen. A low premium on an older policy can also carry a discount that does not transfer.
5. Will my lender make me buy flood insurance?
If the building sits in a mapped special flood hazard area and the loan is federally regulated or insured, yes. Federal law requires flood insurance covering at least the outstanding principal balance of the loan, or the maximum coverage available for that property type, whichever is less. A cash buyer sits outside that requirement.
A strong answer separates the lender's minimum from what would actually replace the building. The required amount protects the loan, not the owner. Ask the lender for the flood determination in writing early, because it drives the escrow and the monthly payment.
Paying cash and skipping flood coverage in Gulf Shores is a decision, not an oversight, and it deserves to be made on purpose. Wind and flood are separate policies here. The Alabama wind pool states plainly that flood is not covered under most property policies, including its own.
6. How much does a flood policy actually cover?
National Flood Insurance Program limits for a home are $250,000 on the building and $100,000 on contents, bought as separate coverage. A new policy takes effect 30 days after purchase. There is no wait when the policy is bought while making, increasing, extending or renewing a mortgage, and no wait when coverage is changed at renewal. Contents coverage is not automatic.
A strong answer walks through what sits below the lowest floor. Coverage for enclosures, stairs and mechanical equipment under an elevated house is limited. Ask the insurance agent to show the coverage list, then price excess flood coverage above the federal limits to close the gap.
Assuming a condominium unit is fully covered by the association's flood policy is worth checking rather than believing. Building coverage and unit interior coverage are different things. Read the association's declarations page before the inspection period closes.
7. What is the 50 percent rule, and why does it matter for a remodel?
Federal floodplain rules define a substantial improvement as work costing 50 percent or more of the market value of the structure before the work begins. Substantial damage applies the same 50 percent test to the cost of repair. Cross either line and the building has to meet current floodplain standards, not the ones it was built under.
A strong answer runs that arithmetic before the offer on any older beach house a buyer plans to renovate. Gulf Shores enforces the 2024 International Building Code and International Residential Code, effective July 1, 2024, alongside its own flood damage prevention article. Ask the building department how it values a structure for this test.
Planning a full renovation on an older low house without checking this rule is how a kitchen project turns into elevating a building. The rule is not a trap and it is not negotiable. The cheapest time to learn the number is before the offer, not after demolition starts.
8. Will the seller tell me if the house has flooded before?
Not necessarily. Alabama follows caveat emptor for used residential property, so a seller generally has no duty to volunteer a past flood. The duty appears in three places: a known condition affecting health or safety that a buyer cannot readily see, a fiduciary relationship between the parties, and a direct question, which has to be answered truthfully.
A strong answer is a written question, sent through the agent, asking whether the property has ever flooded and whether any flood claim has been filed. Buyers comparing Gulf Shores realtors can ask each one which streets take water in a hard rain.
Leaning on a verbal all clear is the expensive version of this. An as is clause does not license an evasive or misleading answer, and it does not license silence in the face of a direct question. Put the question in writing and keep the reply.
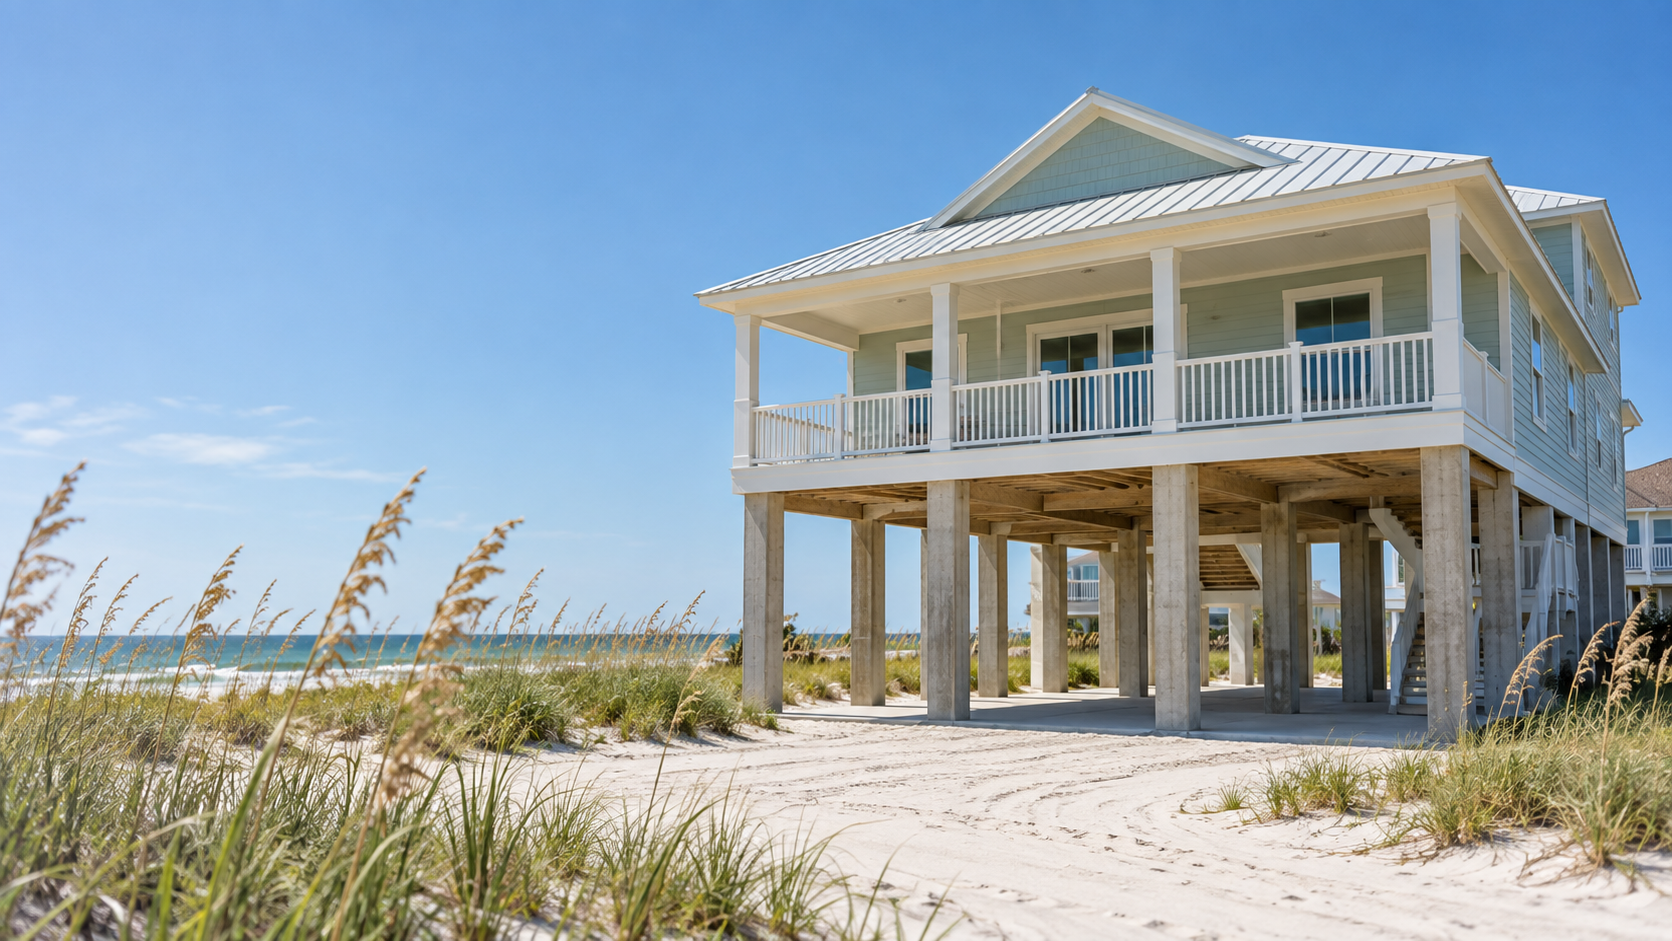
Zone AE Versus Zone VE
How zone AE and zone VE differ on a Gulf Shores flood map.
Frequently Asked Questions
What's the worst flood zone to be in?
On a coastal map, VE is the highest hazard designation, because it adds high velocity wave action to the same base flood that defines an AE zone. Since flood insurance is now rated building by building, the zone alone no longer settles what a property costs to insure. Treat the zone as the building rule and the quote as the price.
Does homeowners insurance cover flood damage?
No. Homeowners and renters policies do not typically cover flood damage, and the Alabama wind pool says the same about its own property policies. Flood is bought separately, through the federal program or a private carrier. On the Alabama coast a buyer is usually looking at three things: property coverage, wind coverage and flood coverage.
Is flood insurance required for a condominium in Gulf Shores?
It depends on the loan and on what the association already carries. Many associations hold a master flood policy on the building, which can satisfy a lender for the structure while leaving the unit interior and contents uncovered. Ask the association for the declarations page and ask the lender in writing what it needs.
What should a buyer do first when a flood zone shows up on a listing?
Pull the current map panel, ask Baldwin County to search for an elevation certificate, and get a flood quote on the address. Those three steps take a few days and settle most of the question. In Gulf Shores and Orange Beach, where Heather Loper & Associates works, that sequence runs inside the inspection period.
Is the bay side safer than the Gulf front?
Not automatically. Mapping reflects surge, wave exposure and elevation rather than distance from the beach, so a bay or bayou lot can still sit in a mapped high risk zone. The only reliable answer is the panel for that parcel, read next to an elevation certificate for that building.
Check the flood picture with Heather Loper & Associates
Heather Loper & Associates works Gulf Shores and Orange Beach and can pull the map panel, chase the elevation certificate and line up a flood quote while a buyer is still inside the inspection period. Buyers comparing the best real estate agents in Gulf Shores should ask each one how they handle those three steps.
or another way